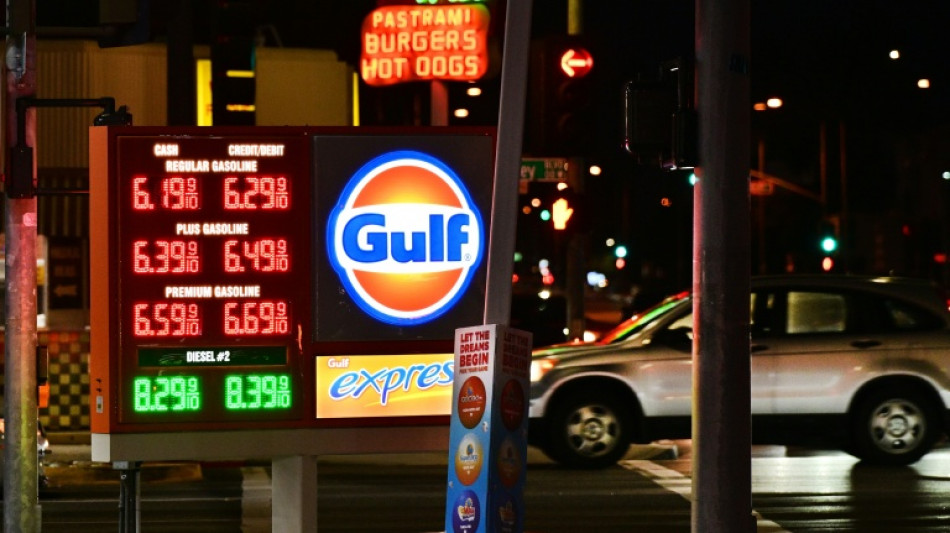
Policymakers take on energy shock, rising debt at IMF-World Bank meetings / Photo: Frederic J. BROWN - AFP/File

 London
 13 °C

 Manchester
 8 °C
 Glasgow
 6 °C
 Dublin
14 °C
 Belfast
13 °C
 Washington
19 °C
 Denver
28 °C
 Atlanta
19 °C
 Dallas
 32 °C
 Houston Texas
 32 °C
 New Orleans
29 °C
 El Paso
31 °C
 Phoenix
27 °C
 Los Angeles
21 °C
San Diego
21 °C
San Francisco
 17 °C
Chicago
24 °C
Minneapolis
32 °C
Seattle
15 °C
Portland
17 °C
Salt Lake City
20 °C
Las Vegas
 21 °C
Miami
30 °C
Jacksonville
28 °C
San Antonio
33 °C
Bermuda
26 °C
Nassau
14 °C
Iqaluit
-4 °C
Yellowknife
6 °C
Anchorage
6 °C
Fairbanks
6 °C
Barrow
-1 °C
Calgary
 1 °C
Edmonton
19 °C
Winnipeg
8 °C
Goose Bay
14 °C
Halifax
13 °C
Boston
13 °C
Ottawa
18 °C
Toronto
15 °C
Detroit
16 °C
Cleveland
17 °C
New York
15 °C
Baltimore
19 °C
Philadelphia
17 °C
Nuuk (Godthåb)
1 °C
Hong Kong
 27 °C
Singapore
28 °C
Melbourne
28 °C
Canberra
15 °C
Adelaide
15 °C
Darwin
26 °C
Perth
11 °C
Fort Worth
32 °C
Honolulu
29 °C
Sydney
23 °C
Johannesburg
18 °C
Dubai
31 °C
Mumbai
31 °C
Zürich
10 °C
Tokyo
18 °C
Seoul
17 °C
Delhi
 23 °C
Beijing
13 °C
Riyadh
30 °C
Prague
7 °C
Pennsylvania
15 °C
Valletta
22 °C
Manama
32 °C
Warsaw
8 °C
Stockholm
8 °C
Finance ministers and central bankers meet in Bangkok this week for the annual gatherings of the International Monetary Fund and World Bank, with the global economy buffeted between the US-Iran war's energy shock, rising debt pressures and the AI boom.
The meetings run from Monday through Saturday in the Thai capital, and will see policymakers tackle some stark choices, with the IMF calling on governments to rein in spending even as vulnerable citizens' needs may be growing in the face of surging inflation and climate risks.
The week will see a combination of high-level closed-door meetings, public events and policy announcements from the world's top economic officials.
On Tuesday, the IMF will unveil its global economic forecast, along with detailed regional outlooks through the week, as policymakers set about tackling the challenges darkening the economic horizon.
"To put it simply, the global economy is being pulled in two opposite directions: a negative energy supply shock and a positive demand shock from AI," said IMF chief Kristalina Georgieva at an event kicking off the meetings in Singapore last week.
"The combined impact of these two forces is highly uneven across the world."
- 'Perfect storm' -
Chief among the concerns will be the economic fallout of the US war on Iran, which has seen energy prices skyrocket as Tehran's retaliatory action has targeted Washington's Gulf allies and curtailed global oil and gas supplies.
The IMF has warned that the effects of the shock have been unequal, with developing countries reliant on imported energy hit the hardest.
Despite the crisis, the Fund has called on countries to curb spending on subsidies and instead build their fiscal buffers after years of shocks since the pandemic.
Critics say that approach is just not feasible for low-income countries, and that multilateral lenders need to do more.
"The poorer member states of the IMF and World Bank are in distress from spillovers of the Iran war, rising interest rates in the West, and a climate crisis exacerbated by El Nino," said Kevin P. Gallagher, director of Boston University's Global Development Policy Center.
"The IMF and World Bank are not meeting this moment. They need an ambitious response that provides short-term emergency liquidity alongside longer term financing to make their economic growth paths less vulnerable to these shocks."
And the needs are great, according to the United Nations Development Programme (UNDP).
The combined shocks "could leave millions more in poverty as developing countries struggle to sustain support for households," UNDP warned in a new report on Sunday.
"Surging oil and food prices leave millions of families with no safety margin," said UNDP Administrator Alexander De Croo.
"We are witnessing a perfect storm that could throw tens if not hundreds of millions of people back into poverty."
In the developing world, he added, governments are being forced to make the "impossible" choice between cutting support for their poorest citizens or risking their entire development agenda.
- 'AI is here' -
Advanced economies in Europe and the United States have weathered the storm from the rising energy prices better, but have not been immune to surging inflation fuelled by those price increases, which have begun to bleed into other goods.
That inflation has seen central banks around the world raise interest rates in an effort to curb rising prices, tapping the brakes on economic activity.
Still, advanced economies have seen a boom in investment in artificial intelligence technology drive stock markets to new highs and bolster economic growth.
The IMF has said that the amount invested in AI will likely outstrip the capital put into building the railroads, the electricity grid or global telecommunications networks.
"Love it, hate it, or fear it, AI is here, rapidly becoming a key driver of countries' relative fortunes in the world economy," said Georgieva last week.
Several events through the week will focus on AI's impact, including in developing countries that may not be exposed to its economic benefits as they lie outside its supply chains.
The week will also see several key meetings on the sidelines, including of G20 finance ministers, where spiking bond yields will be high on the agenda.
A notable absence at that meeting will be US Treasury Secretary Scott Bessent, who will skip due to "domestic engagements", a department official said on Friday.
S.Denis--PS